Power the way businesses pay vendors
Give your customers more ways to fund & deliver vendor payments through one licensed integration
network connections
transactions settled daily
annualized run rate
(as of Dec 2025)
Every vendor payment, covered
Pay bills by card
Give your customers the flexibility to pay by card while suppliers receive funds through their preferred method
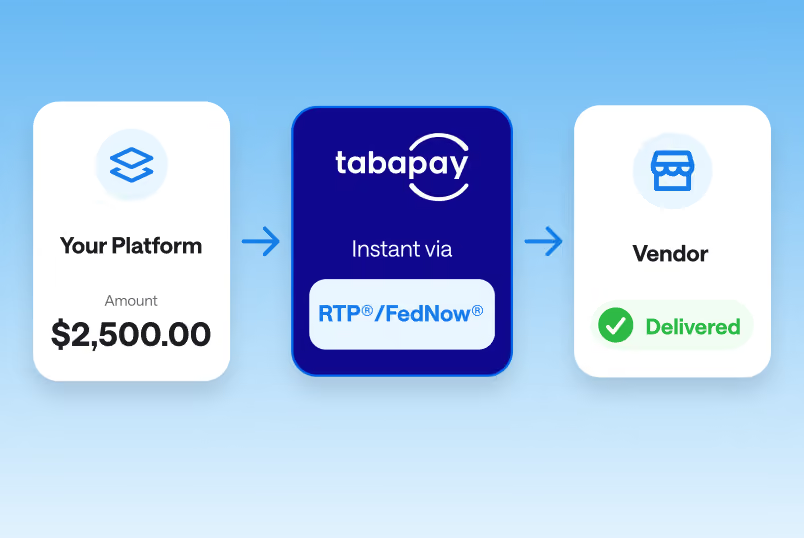
Pay bills in real time
Enable businesses on your platform to pay vendors in real time through RTP® & FedNow®
Use payment links
Support reliable, cost-effective vendor payments directly to bank accounts through ACH
Built to power collections behind the scenes
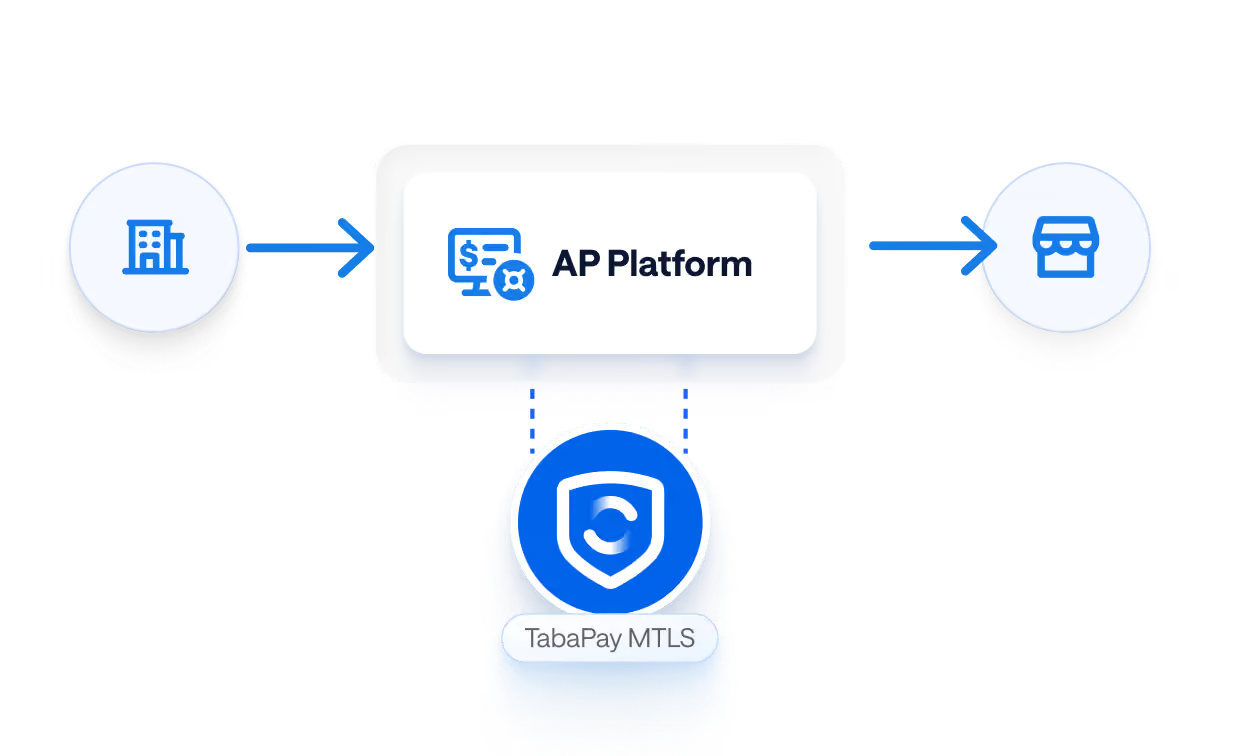
Licensed on your behalf
Cover the full payment, from buyer to vendor
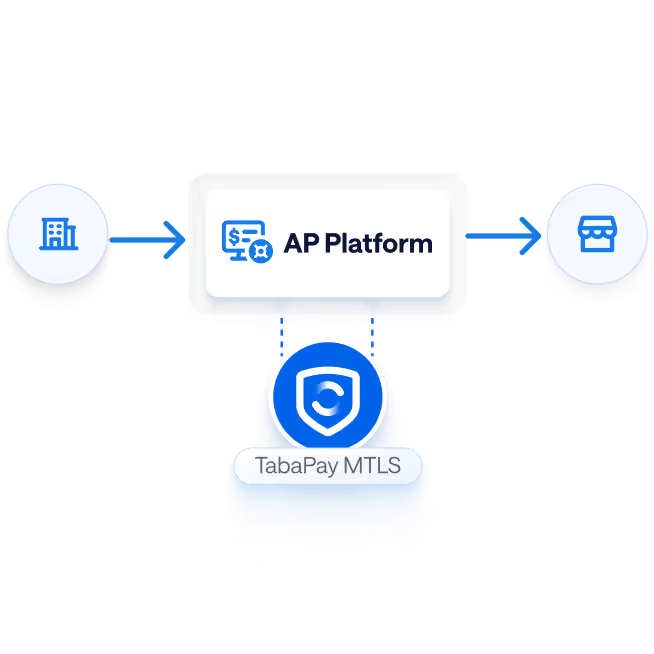
TabaPay acts as money transmitter or agent of payee
Handle BPSP registration & segregation
Direct network access
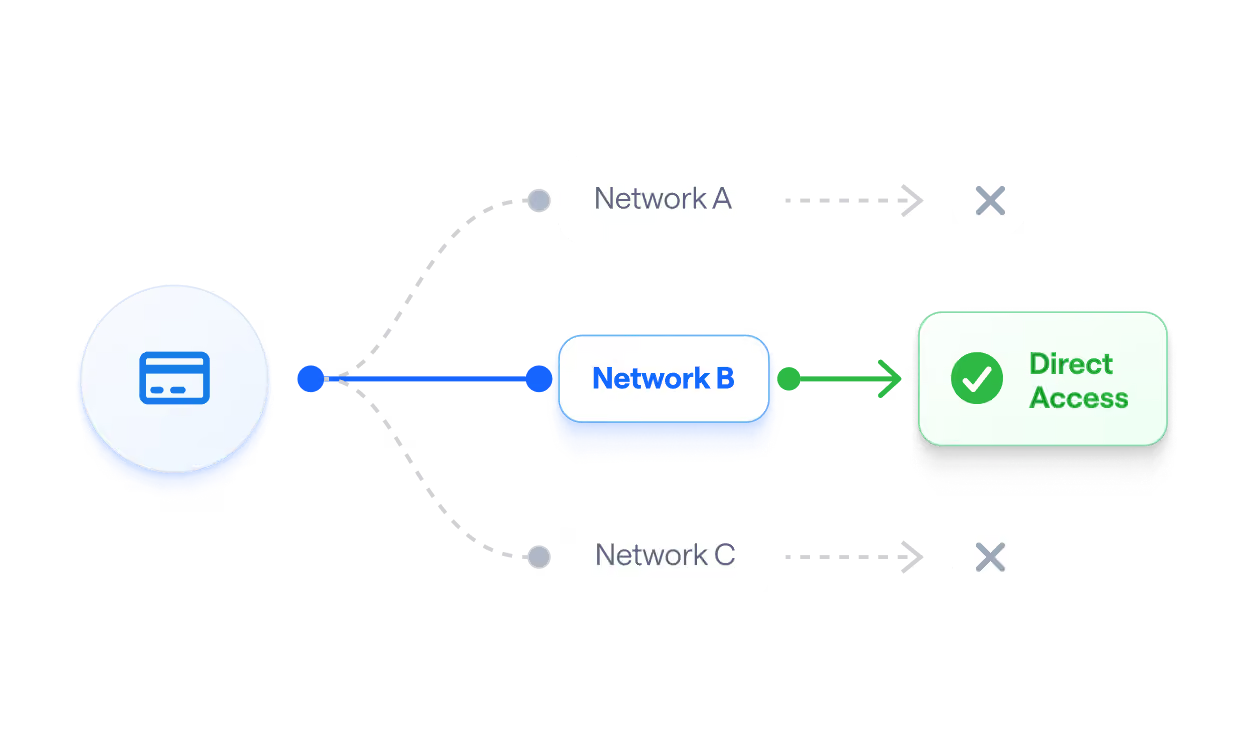
Connect directly across 15+ card networks
Accept Amex through OptBlue, no separate contract required
Skip the middle layer between you & the networks
Designed for enterprise buyers
Lower processing costs on eligible B2B card payments with enhanced data
Improve margin as enterprise volume grows
Ready for RFP-driven contracts
One integration, every method
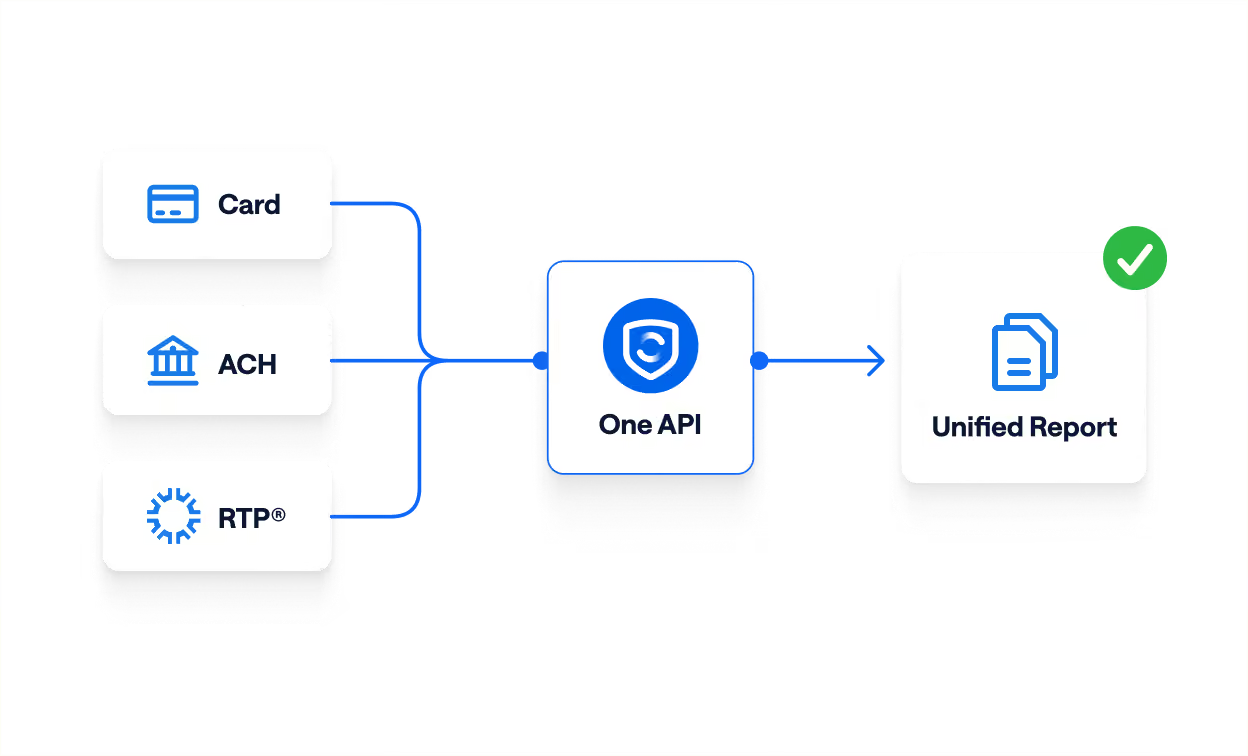
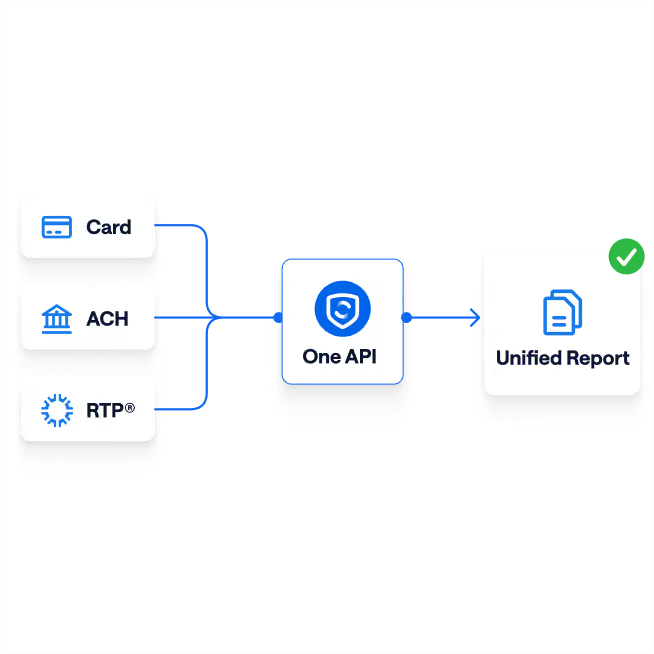
Accept ACH, RTP®, & card through one integration
Send PCI-compliant payment links — no card data touches your system
Get one report across every method
Support for all kinds of accounts payable
AP automation platforms
Embedded finance & vertical software
Payroll & HR platforms
Banks & credit unions
Pay vendors, stay compliant
Start paying vendors faster, with compliance built into every payout
Frequently asked
questions
No. Most AP platforms already run on an existing processor or bank relationship, and that dependency is usually what limits which rails you can offer and how fast money settles. TabaPay handles the money movement underneath what you've already built, so invoice capture, approvals, and ERP integrations stay as they are.
Vendors get paid same day on push-to-card and RTP®, against a standard two-to-three-day ACH cycle. Both run through the same integration, so you're not choosing one rail for every vendor.
Yes. Paying a vendor is a push motion and collecting from the business is a pull motion, and platforms handling both often maintain separate vendor relationships or separate rail sets for each direction. Both run through the same integration here.
Vendors can receive payment to a card or to a bank account. Card payouts go out over push-to-card, bank payouts over RTP® or ACH, all through a single integration. Vendors get paid the way they prefer rather than adapting to whatever single option a platform supports.