- Fraud prevention starts before account funding. Card verification can flag discrepancies that warrant additional review before money moves.
- Review verification results and transaction behavior together. Name and address mismatches, repeated declines, and rapid outbound transfers can reveal patterns that individual signals miss.
- Layered controls help reduce risk without broad restrictions. Authentication, limits on repeated attempts, and targeted monitoring can address suspicious activity while minimizing disruption to legitimate customers.
International Fraud Awareness Week (November 15–21, 2026), led by the Association of Certified Fraud Examiners (ACFE), is a global initiative dedicated to raising awareness, promoting education, and strengthening fraud prevention efforts. As a proud supporter of Fraud Week 2026, TabaPay is committed to supporting these efforts and helping businesses better understand and respond to evolving fraud threats.
As fraud schemes become increasingly sophisticated, effective prevention requires more than reacting to potentially suspicious transactions after they occur. It requires a proactive, layered approach that combines fraud awareness, transaction monitoring, verification tools, and actionable insights to identify emerging risks and mitigate potential losses.
At TabaPay, we recognize that fraud prevention is a shared responsibility. By providing payment insights, fraud prevention tools, and risk guidance, we help clients strengthen their fraud controls while balancing security with a seamless experience for legitimate customers.
In “The tip that wasn’t,” we shared how connecting customer payments to worker payouts helped uncover insider fraud on a digital tipping platform.
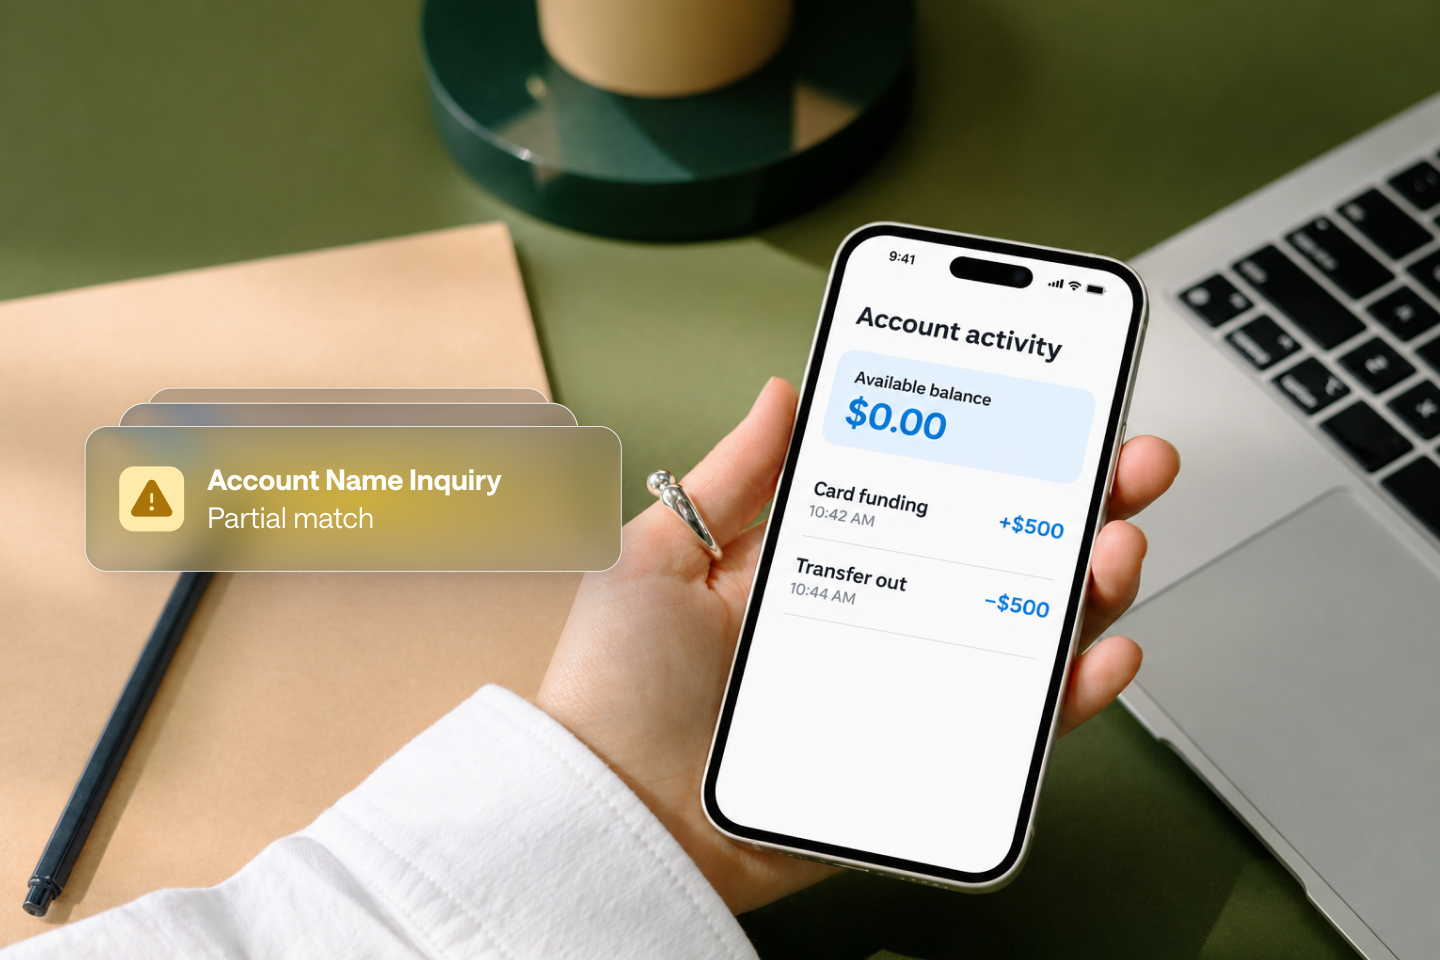
This story turns to digital banking, where fraudsters used stolen debit card information to fund accounts and quickly transfer the money elsewhere. It highlights how verification results, repeated funding attempts, and rapid outbound transfers can help reveal a pattern of unauthorized activity.
Setting the scene
The client: A digital banking platform that allows customers to fund their accounts using external debit cards.
The flow: An Account Funding Transaction (AFT) to fund an account with a debit card, followed by outbound transfers.
The fraud: Unauthorized account funding using stolen debit card information, commonly referred to as "load and go" fraud.
What happened
A group of fraudsters opened accounts using stolen or fraudulent information and attempted to link debit cards belonging to legitimate cardholders. They initially submitted small transactions to identify cards that could be successfully used for funding.
Once successful, the fraudsters funded the accounts and rapidly transferred the funds elsewhere, attempting to move the money before the unauthorized activity was identified.
The warning signs
- Name and address mismatches. Account Name Inquiry (ANI) and Address Verification Service (AVS) responses identified potential discrepancies between payment card information and customer-provided information, indicating the need for additional review.
- Excessive transaction attempts. Repeated authorization declines, and multiple attempts involving the same payment cards suggested potential card testing.
- One card, multiple identities. Activity involving the same underlying payment card across multiple customer accounts or identities may indicate unauthorized card use. Payment Account Reference (PAR), where available, can help correlate payment card activity.
- Rapid funding and withdrawal activity. Accounts receiving funds and transferring them out shortly afterward may present elevated fraud risk, particularly when combined with other potentially suspicious indicators.
Fraud prevention strategies
The scenario illustrates several controls digital banking platforms can consider to reduce exposure to unauthorized account funding.
- Strengthen card verification. Incorporating ANI, AVS, and CVV2, where supported, can provide additional verification signals when customers link payment cards or initiate funding transactions. These signals should be evaluated alongside other account and transaction risk indicators.
- Apply risk-based authentication. Additional authentication measures, including 3D Secure (3DS), where supported and applicable, may help mitigate fraud associated with higher-risk transactions.
- Limit card testing and excessive retries. Establishing appropriate restrictions on failed card-linking attempts, authorization retries, transaction frequency, and funding amounts can help identify and disrupt potentially suspicious behavior. These controls may involve both client-managed restrictions and available Real-Time Monitoring capabilities.
- Monitor unusual card activity. Card-level velocity monitoring, transaction limits, and patterns involving multiple identities can help identify activity inconsistent with expected customer behavior.
- Use targeted monitoring. BIN-level trends, fraud reports, and transaction monitoring alerts can help prioritize investigations without automatically restricting legitimate customers based solely on their issuing bank.
- Incorporate reported fraud into ongoing monitoring. Reviewing reported fraud and chargeback activity can help identify emerging patterns and inform adjustments to monitoring rules, account restrictions, and other fraud prevention controls.
Protecting legitimate customers
Effective fraud prevention requires balancing security with the customer experience.
Rather than applying broad restrictions to all customers, digital banking platforms can use layered verification and risk-based monitoring to identify potentially suspicious activity while minimizing unnecessary disruption to legitimate account holders.
In this scenario, the platform applied targeted restrictions to the accounts associated with the suspicious activity rather than tightening controls for its entire customer base. Funds that had not yet been transferred out were held pending review, and the payment cards involved were added to monitoring controls to help prevent further attempts to link them. Legitimate account holders continued to fund their accounts without interruption while the platform completed its review.
Regularly reviewing authorization trends, fraud reports, chargeback activity, and verification results can help businesses evaluate the effectiveness of their controls and adjust their strategies as fraud patterns evolve.
Consumer fintech banking platform Current saw the benefits of using this approach by implementing ANI during cardholder onboarding. In a three-month pilot, full name matches were associated with a 153% increase in card attachment rates and a 57% reduction in chargebacks compared with no matches.
The Takeaway: Fraud prevention begins before funds move. By combining card verification, transaction monitoring, appropriate velocity controls, and ongoing review of fraud indicators, businesses can identify potentially suspicious activity earlier and take targeted action to reduce potential losses.
Fraud prevention doesn't stop after Fraud Week
Fraud threats continue to evolve, and effective prevention requires ongoing awareness, adaptability, and a proactive approach to managing risk. The goal isn't simply to block suspicious transactions, but to recognize emerging fraud patterns, apply appropriate controls, and make informed decisions that help protect businesses and their customers without creating unnecessary friction.
Across industries such as digital banking, lending, on-demand payroll, gaming, and the gig economy, businesses face unique fraud challenges. A layered fraud prevention strategy that combines transaction monitoring, verification tools, actionable reporting, and ongoing risk assessments can help identify suspicious activity earlier and reduce potential exposure.
At TabaPay, we're committed to supporting our clients with the tools, insights, and guidance they need to strengthen their fraud prevention programs while maintaining a positive experience for legitimate customers.
Fraud awareness does not end when Fraud Week does. Staying informed, regularly evaluating fraud controls, and adapting to emerging threats are essential to building a stronger, more resilient payments ecosystem.
To learn more about TabaPay's fraud prevention capabilities and how they may support your business, connect with our team.