Fund for less & pay out instantly
Lower remittance funding costs, enable instant cross-border push-to-card payouts, & preserve working capital with less prefunding requirements & same-day settlement
FX pricing through
Visa & Mastercard
countries & territories
US card-not-present provider (Nilson Report)
From funding to payout
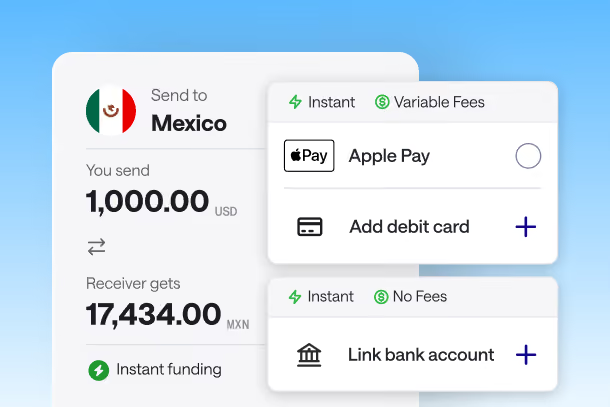
Fund remittances
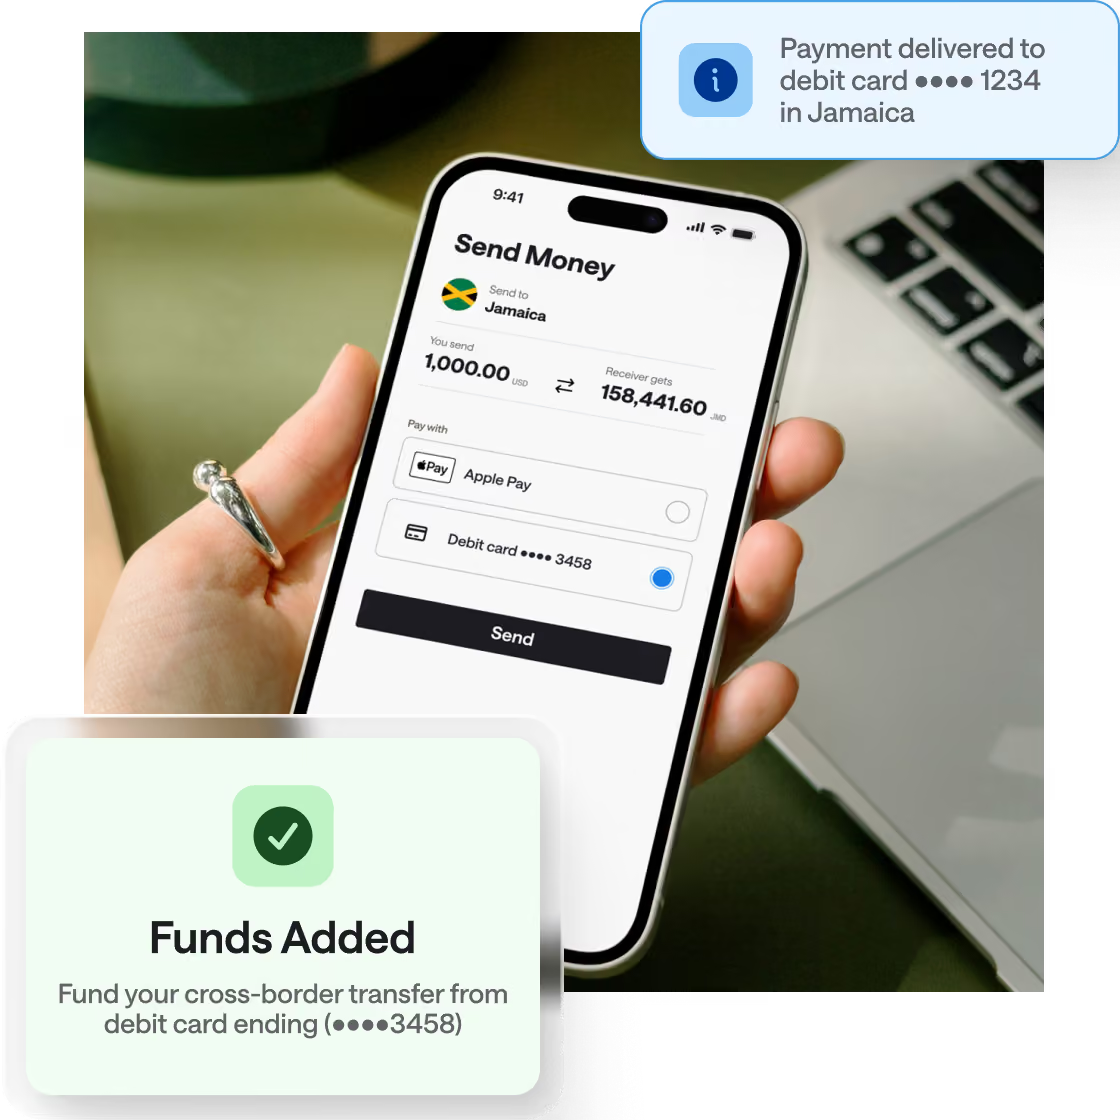
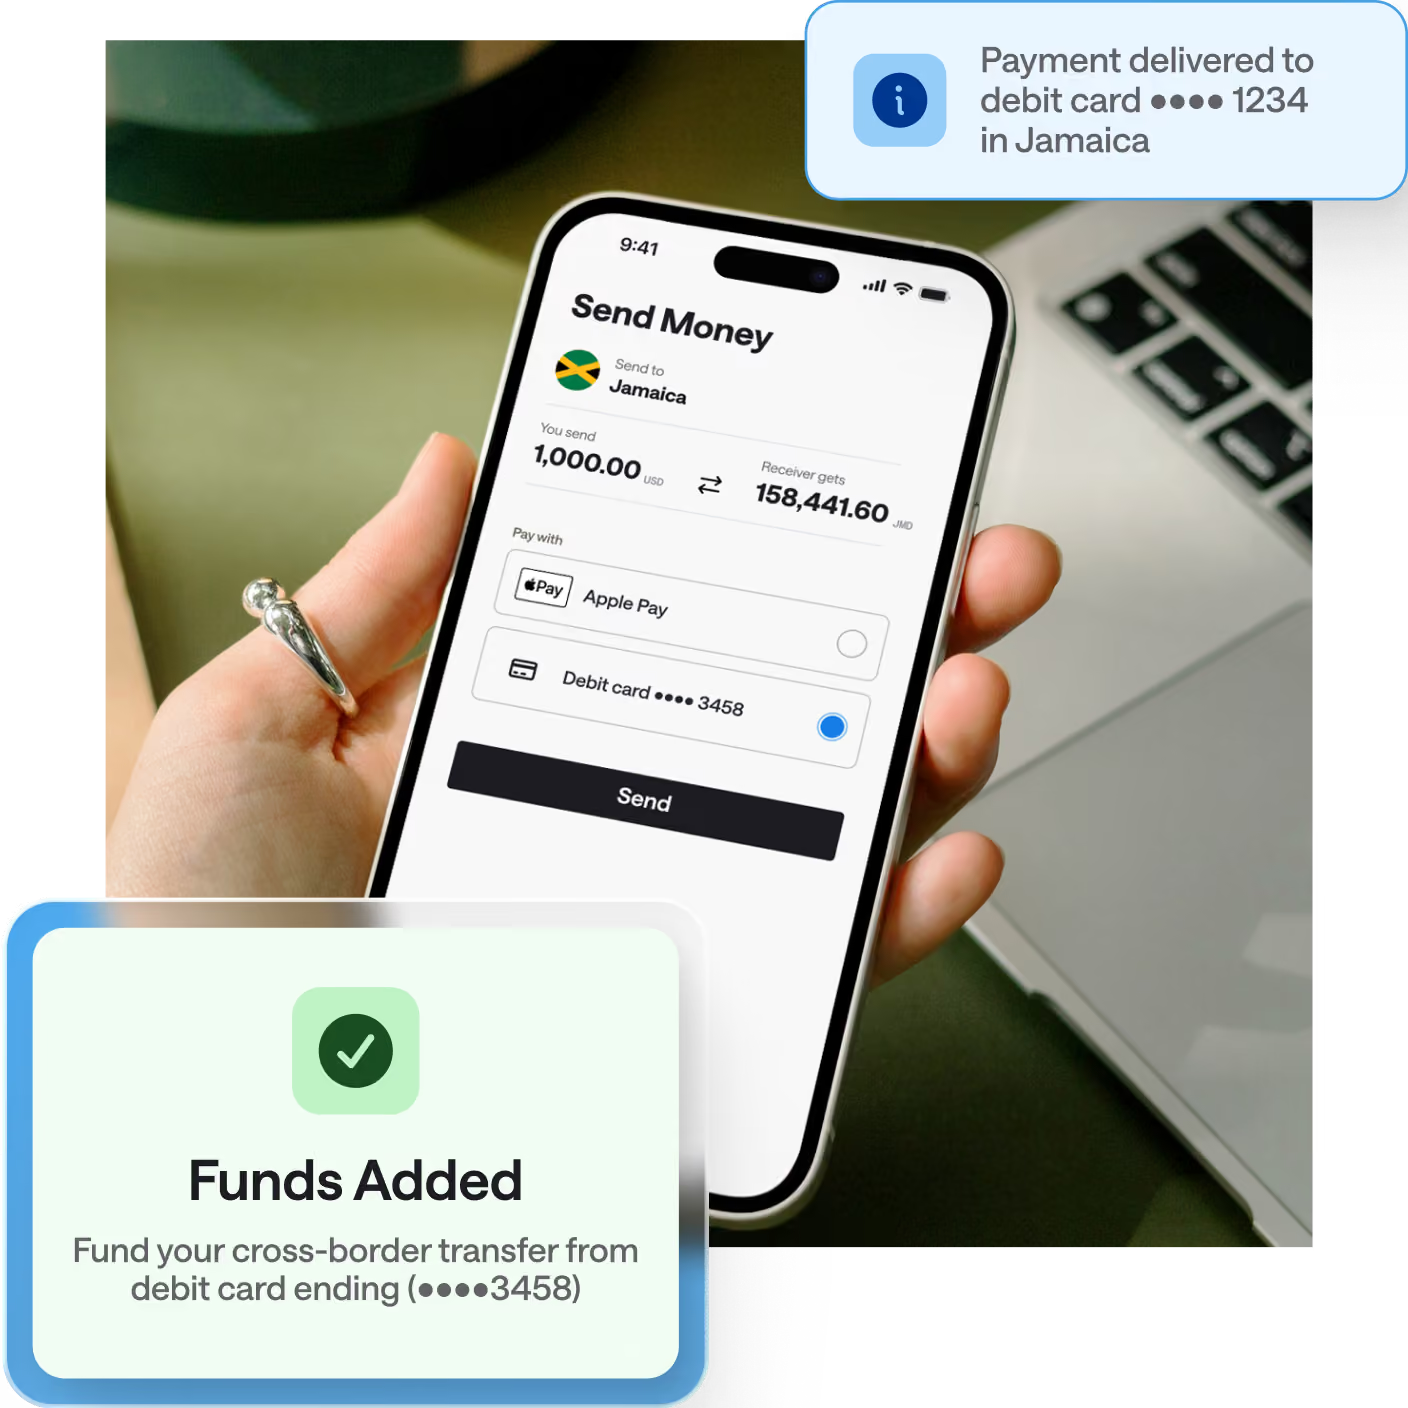
Give senders convenient ways to fund remittances instantly with debit cards across digital & in-person experiences
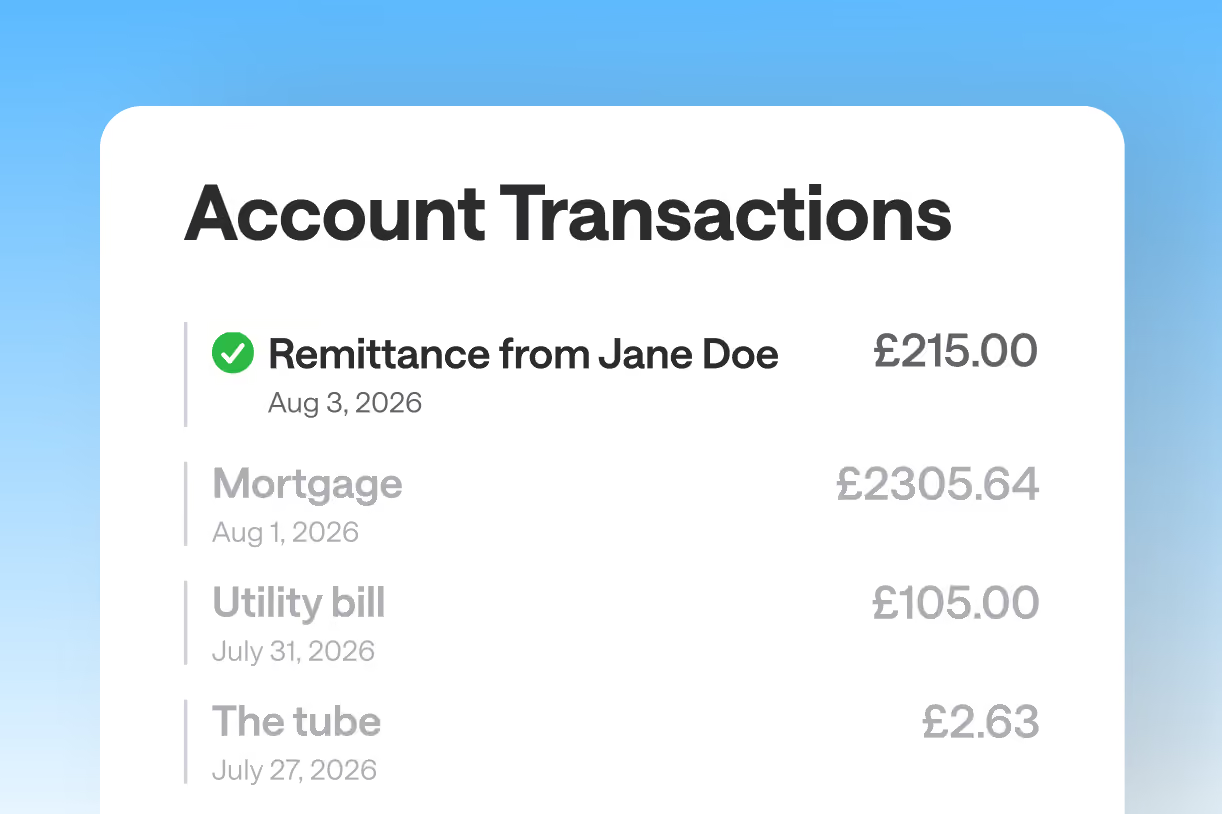
Deliver cross-border payouts
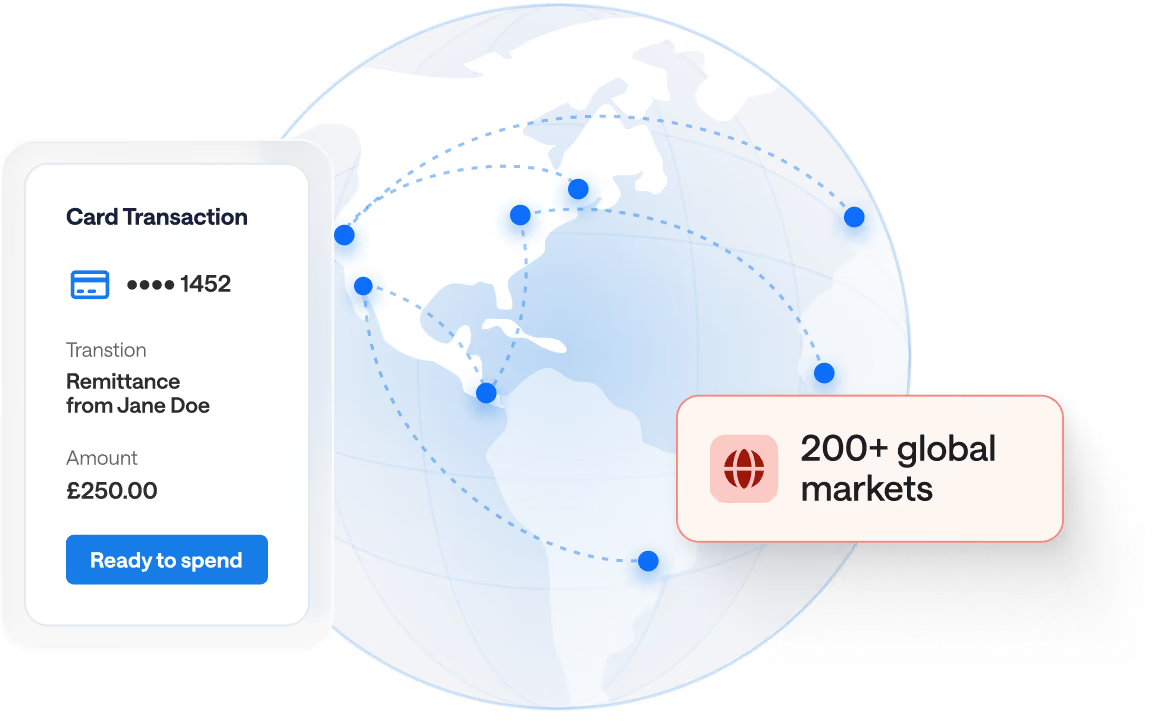
Send funds directly to eligible cards across 200+ global markets with cross-border push-to-card
Built for every step
of a remittance
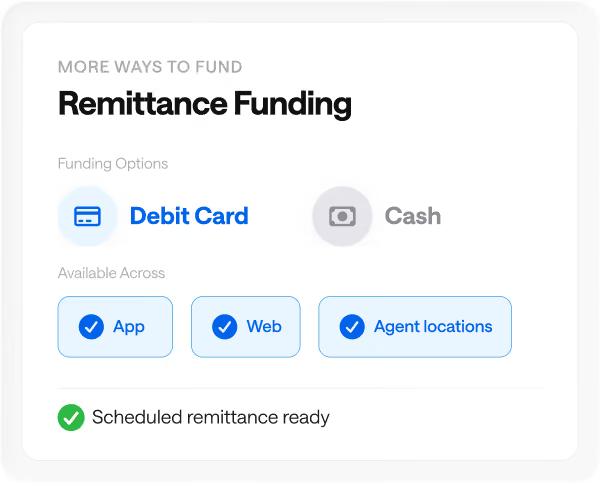
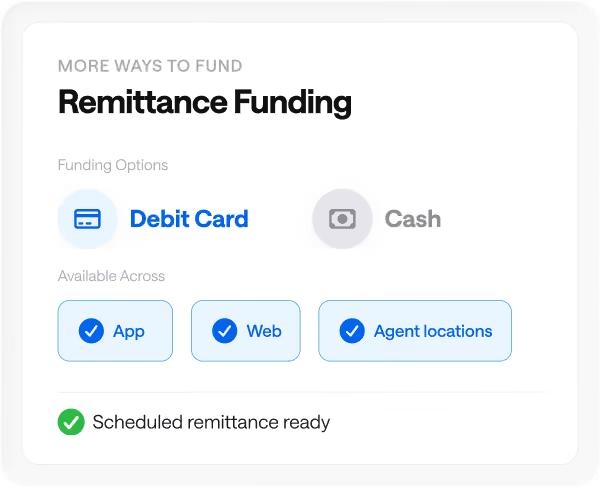
Expand how customers fund remittances
Give customers more ways to fund remittances with debit card acceptance
Enable omnichannel funding across digital & in-person experiences
Reduce reliance on cash collection & the operational complexity that comes with it
Expand how you deliver remittances
Deliver payouts to eligible cards in 200+ countries & territories in origination currencies (USD or CAD) or eligible local currencies
Reach global markets through a US-based hub model without managing local processor relationships country by country
Return funds quickly to senders with domestic push-to-card when a remittance can’t be completed
Improve your payment economics
Access competitive Account Funding Transaction (AFT) & cross-border Original Credit Transaction (OCT) pricing
Lower transaction costs with least-cost routing across 15+ direct network connections & competitive network pricing
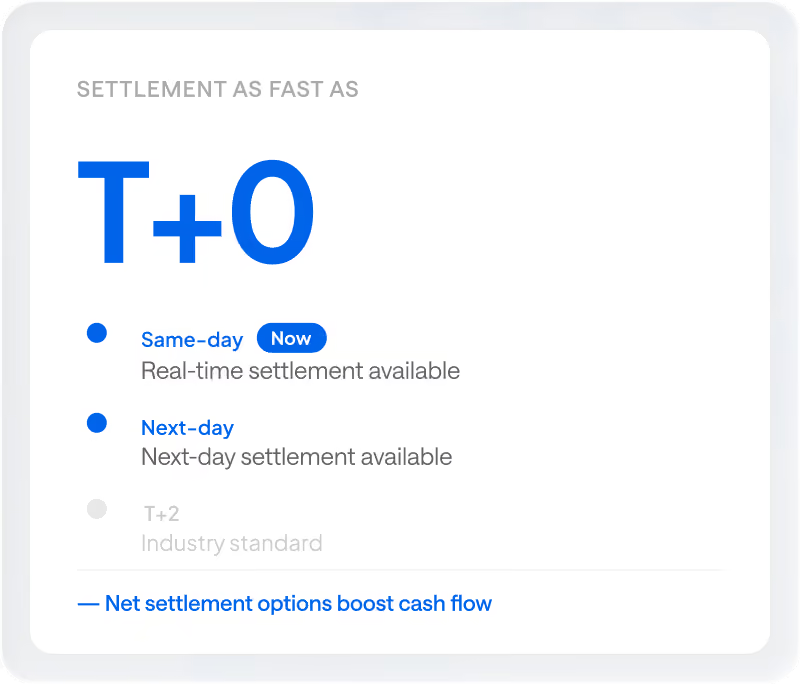
Preserve working capital with payouts that don’t require prefunding & accelerated same-day settlement with AFT
Scale remittance with confidence
Keep remittances moving on infrastructure backed by 99.99% platform uptime
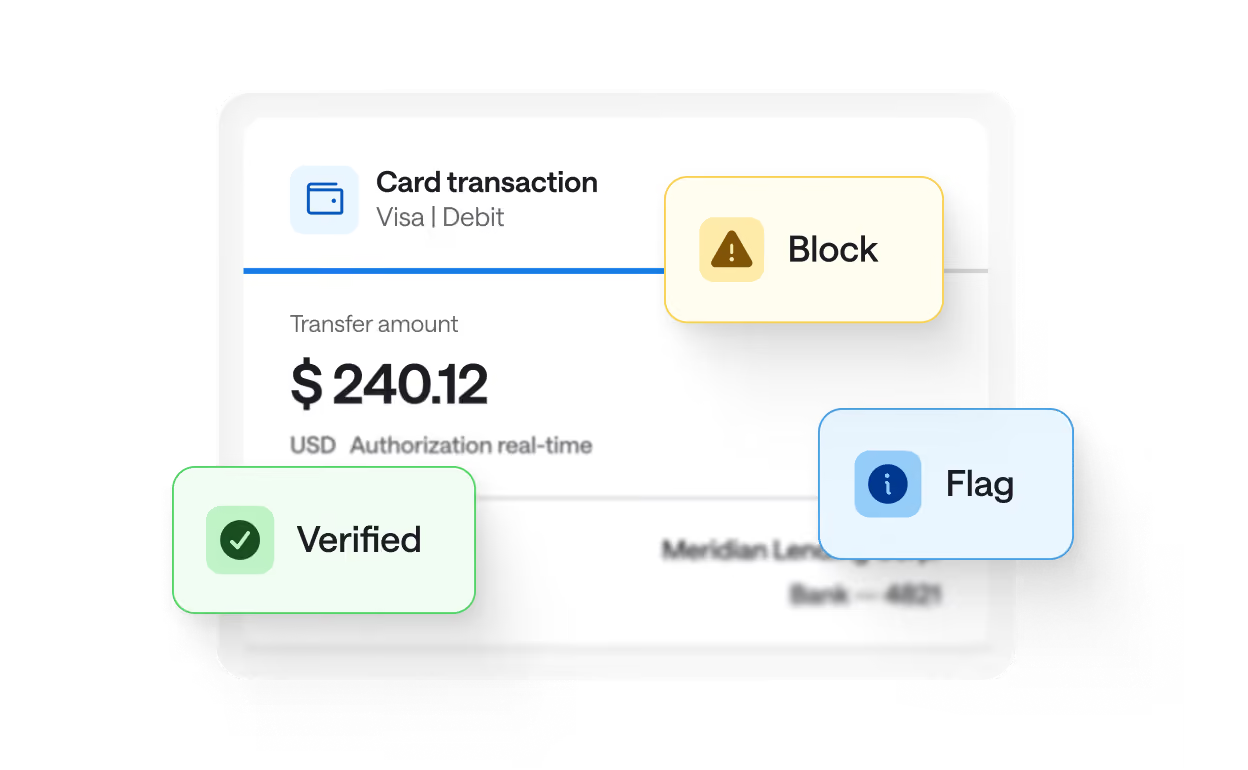
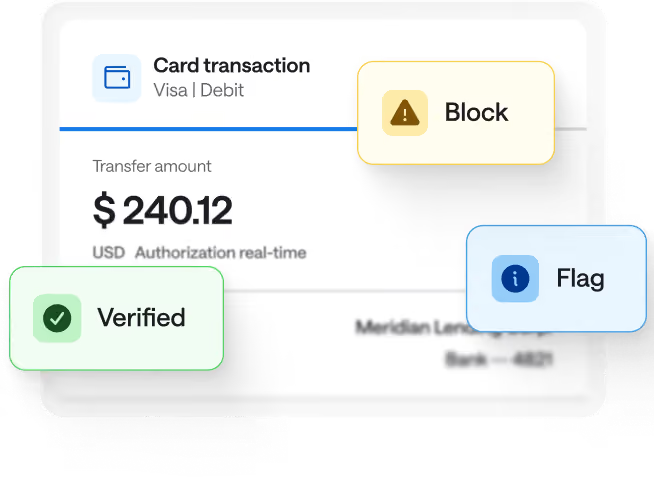
Manage fraud with customizable risk controls & card security tools like AVS, ANI, & 3D Secure
Monitor transactions in real time to identify & respond to risk faster
Move money faster & use less capital
Improve funding conversion, lower payment costs, & expand payout reach globally
Frequently asked
questions
TabaPay helps remittance providers support both sides of the transaction, from funding remittances with debit cards to delivering cross-border payouts to eligible cards. Providers can use TabaPay’s card and bank connectivity to support the payment flows that fit their business model.
Eligible providers can enable customers to fund remittances with debit cards through Account Funding Transactions (AFTs). Card funding can support digital and in-person experiences, giving providers an omnichannel alternative or complement to cash collection.
Yes. TabaPay enables cross-border push-to-card payouts to eligible Visa and Mastercard cards across supported markets. This can help providers expand recipient reach without building and managing individual network connections in every market.
TabaPay can enable eligible card payouts across 200+ countries and territories through Visa and Mastercard connectivity. Availability, supported currencies, and delivery speed vary by market, network, and receiving institution.
Cross-border push-to-card can deliver funds in minutes where fast-funds capabilities are supported. Actual availability and posting times vary by destination, network, and receiving institution.
TabaPay can help providers optimize the economics of card-funded remittances through eligible AFT processing, competitive pricing, and direct network connectivity. Providers can also use TabaPay alongside existing network relationships to expand capabilities while maintaining flexibility in how they manage their remittance business.
For eligible transactions, providers can use domestic push-to-card to expedite refunds back to a sender’s card when a remittance cannot be completed, helping customers regain access to their funds faster than with traditional refund methods.
TabaPay provides fraud and risk capabilities that help providers protect card-funded remittance flows, including customizable risk controls and card security tools such as AVS, ANI, and 3D Secure. Real-time transaction monitoring can provide additional visibility into payment activity.