- Meet borrower expectations with faster disbursements & repayments. Real-time payment options can give borrowers faster access to funds while helping lenders improve repayment visibility and capital efficiency.
- Strengthen fraud controls & partner-bank relationships. Verification tools such as Address Verification System (AVS), Account Name Inquiry (ANI), and 3-D Secure (3DS) can help lenders manage fraud risk, while diversified repayment options can reduce reliance on ACH.
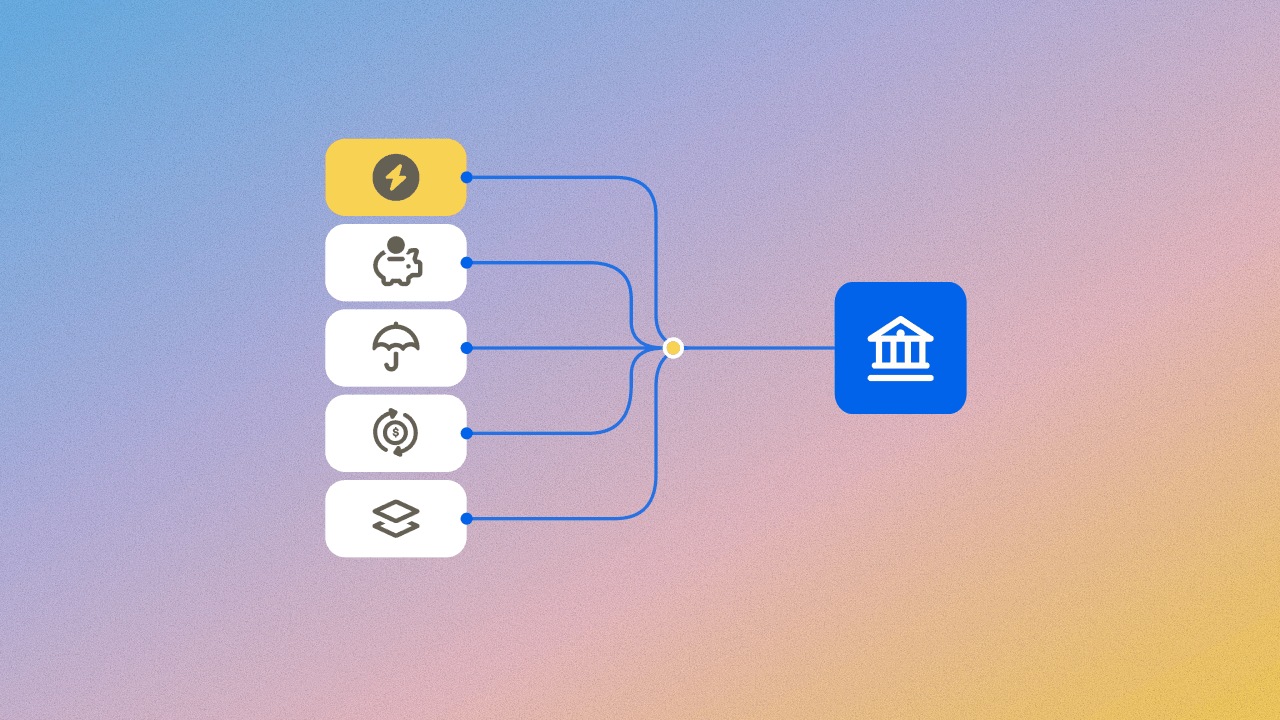
- Offer more payment choices without adding unnecessary complexity. A single API supporting card, ACH, Real-Time Payments (RTP), FedNow, and wire transfers can reduce operational overhead, improve reliability, and let borrowers use their preferred payment methods.
The 5 questions that lenders need to ask themselves
Lenders have a few options when they want to stand out to potential borrowers. They might offer a remarkable APR, underwrite traditionally underserved audiences, or leverage memorable marketing.
Traditionally, one or more of these were typically sufficient to succeed. But now, a lender might lean on all three and still face stagnating growth.
In the last few years, money movement—the process of actually disbursing loans and accepting repayment—has emerged as a key differentiator. As borrowers realize that near-instant disbursements are possible, they’ll be hesitant to settle for anything less. Rapid, reliable money movement confers a huge array of benefits to lenders behind the scenes as well.
Is your approach to money movement helping you stay ahead of your competitors? You can ask yourself five questions to figure out where you stand. If your answer to any of them is “no,” it’s worth reevaluating the way you approach money movement.
Am I meeting borrower expectations for disbursement speed?
When borrowers request a loan, they generally need the disbursement as soon as possible. They might need to cover emergency expenses, or a bill was larger than anticipated. It goes without saying that these borrowers want access to money quickly — ideally, right away. Yet common methods of disbursement aren’t fast enough to meet consumer preferences.
For decades, disbursements and repayments have commonly traveled through Automated Clearing House (ACH) batch processing. ACH remains a cost-effective and reliable option for many use cases, but standard ACH settlement can take one or more business days. Same Day ACH can accelerate settlement during available processing windows, but it does not operate continuously on weekends and federal holidays. For borrowers who need funds immediately, those timing limits can make real-time options more attractive.
Consumers clearly prefer businesses that can provide near-instant gratification. According to the Federal Reserve, 78% of consumers prefer faster payments, and in a study run by PYMNTS, 77% of consumers would choose instant payments to receive disbursements if that option were available.
Despite strong consumer demand, many borrowers are still waiting for a frictionless disbursement experience. A recent Visa study found that 54% of consumers experienced friction with their most recent payouts, with 39% uncertain as to when funds would arrive and 24% receiving funds late.
Borrowers increasingly value faster access to funds. RTP and push-to-card can enable near-instant disbursement, subject to participating financial institution and eligible card availability. These options operate 24/7/365, while ACH settlement follows defined processing windows and banking days.
Is slow repayment speed putting me at a competitive disadvantage?
It’s not just the speed of disbursements that matters, but the speed at which lenders receive repayments. Every day that funds remain in settlement delays their potential redeployment, reduces capital efficiency, and may increase the lender’s need for external funding.
Over the last few years, rapid repayment options such as Account Funding Transactions (AFTs), which pull funds from an eligible debit card, have emerged. For qualifying lender use cases, network incentive rates may make AFTs a competitive alternative to ACH, although actual cost depends on transaction mix, network eligibility, and provider pricing.
AFTs provide a real-time authorization response, giving lenders immediate visibility into whether a repayment request was approved or declined. Settlement and availability of funds occur separately based on the agreed funding schedule. The faster payment decision can improve certainty and reduce the operational delays associated with returned ACH payments.
Can we keep fraud low in the face of increasing criminal activity?
Lenders have always dealt with the risks of account takeover—a fraudster commandeering a legitimate account and applying for a loan through that account. Perhaps surprisingly, despite modern advancements in security technology, account takeovers are becoming more of a threat, not less.
That’s because major data breaches often provide the credentials necessary for account takeovers, and there are more data breaches than ever before. According to TransUnion, the volume of American data breaches increased by 47% between 2024 and 2025, and, unsurprisingly, suspected digital account-takeover fraud increased by 37% during that period.
As standards for data privacy and crisis remediation increase, it’s increasingly expensive to deal with account takeovers after the fact. According to a 2025 LexisNexis study, each dollar of fraud ultimately costs the lender $5.38, up from $4.16 in 2021.
Lenders can use AVS and ANI as verification signals to compare address and cardholder-name data. 3-D Secure can add issuer-led authentication and risk assessment to card-not-present transactions. Depending on the risk assessment, authentication may occur frictionlessly or require the cardholder to complete an additional challenge.
Can we move payments along customer-preferred rails without substantial overhead?
Every borrower has particular preferences for how they want to receive and repay money. Some prefer to go through their banks, while others prefer card-based payouts.
For this reason, lenders strive to provide customers with multiple rails to choose from, but this can be an unwieldy process. A Federal Reserve study found that nearly half of surveyed businesses were concerned about implementing multiple rails due to high costs, while nearly a third had concerns about security, slowdowns, or an expensive integration process.
Each rail has its own statuses, settlement timing, exception processes, and reporting format. When ACH, card network, RTP, FedNow, and other payment activity live in separate systems, employees have to piece together a complete picture themselves.
To resolve this challenge, it’s critical to implement a single API that can support any of the rails you need. This provides you with the flexibility to send money along any rail—be it card, RTP, FedNow, ACH, or wire—without needing to layer on new integrations or deal with data that lives in silos. Relying on a single API saves time, reduces overhead costs, and improves reliability for borrowers because there are fewer moving parts.
Do recent regulatory changes endanger our relationship with our partner bank?
Lenders need a strong relationship with their partner banks. Those relationships depend in part on managing ACH risk and meeting Nacha requirements.
Banks monitor unauthorized ACH debit returns because elevated return rates create risk and potential rule violations. Lenders with persistent return issues may face additional controls, pricing changes, or termination by their banking partner.
In 2026, NACHA mandated enhanced fraud-monitoring requirements across ACH participants, including originating banks, non-consumer Originators, Third-Party Service Providers, Third-Party Senders, and receiving banks. The rules focus on identifying ACH credit entries suspected of being unauthorized or authorized under false pretenses. These requirements raise expectations for fraud controls, but they are separate from existing unauthorized-return requirements for ACH debits.
Lenders can work with an experienced money movement partner to identify fraud patterns and help reduce unauthorized returns. They may also diversify repayment options with card-based AFTs. AFTs provide a real-time authorization response, although settlement occurs separately and transactions remain subject to network rules, reversals, and disputes.
The Takeaway
Lenders are falling behind because they’re approaching money movement in a suboptimal way. This is leading to an experience that frustrates customers—with unreliable disbursements and unacceptably high levels of fraud—and frustrates lenders—with long waits to receive repayments, strained relationships with bank partners, and inefficient money movement across multiple rails.
In order to stand out and thrive, lenders need a few key capabilities:
- Providing competitive time-to-fund for borrowers by leaning on alternative rails to ACH.
- Receiving repayments quickly and reliably while managing return and dispute risk. · Leveraging verification tools like AVS, ANI, and 3DS to manage fraud risk.
- Maintaining strong partner-bank relationships while meeting evolving Nacha requirements.
- Offering borrowers their choice of rails by which to repay without becoming overwhelmed by complexity.
If you are looking for the best way to address these points and gain a competitive advantage, TabaPay is in an excellent position to help. The company combines unparalleled expertise in lending with a network of 20+ partner banks well-versed in challenging money movement use cases like lending.